It started with a tweet.
Someone sent me a tweet from @SwiftKirk that contained a link to a website called Casino Secrets. I clicked it. What I found was a page devoted to The Elite Turf Club N.V. and dozens of documents purporting to come from the files of the Curaçao Gaming Authority. Business plans. Financial statements. License applications. Corporate structures. Account agreements. Policies. Regulatory reports. Ownership records. Projections. The type of material nobody involved in horse racing wagering is accustomed to seeing laid out in one place.
Before going any further, there is something that needs to be said clearly. Past the Wire cannot independently authenticate every document contained in this collection. We did not obtain them from Elite Turf Club or from the Curaçao Gaming Authority. We had nothing whatsoever to do with obtaining them from the regulator. They were already publicly available when we found them. Follow the Money, which participated in the larger Casino Secrets investigation, has reported that the Curaçao material was obtained from the regulator’s licensing system and that its journalists independently examined original documents when questions arose about information contained in the leaked database.
We downloaded the Elite Turf Club archive, examined the documents, removed exact duplicates from our working set and began checking material facts against information already in the public record. Many of the most significant details were independently corroborated, including Elite’s approximate number of customers, minimum wagering requirements, ownership of its United States entity, the use of AmTote technology, track approval of individual wagering accounts and the basic economics surrounding computer-assisted wagering. We found nothing in that process that gave us reason to believe the documents were fabricated. Further, some of what I saw I knew to be true, and had actually discussed on these pages previously.
For purposes of this article, I am going to treat all the documents as authentic and accurate representations of what they purport to be unless credible evidence emerges showing otherwise. Where something can be independently confirmed, I will say so. Where it cannot, I will say that too. There are questions these documents answer. There are others they raise. There are some we simply could not answer. That is fine with me. I always thought this type of information would become public if the discovery in the Dickey v Elite et al case went further.
Start with the scale.
The business plan submitted in Curaçao describes an operation with roughly twenty customers that handled more than $2 billion in pari-mutuel wagering during 2023. Elite separately told the California Horse Racing Board in September 2024 that its membership generally hovers between twelve and twenty players at any given time. Elite also told the CHRB that each account belongs to an individual person, although that person may employ programmers, modelers and other personnel as part of a wagering team.
Twenty people. Billions of dollars. That alone should tell you we are not discussing a conventional ADW business. Elite is not out buying television commercials looking for $50 depositors. It is not offering a sign-up bonus because the guy watching the third at Gulfstream might become a weekend customer. Its business plan says it does not advertise or promote itself in the traditional sense. Customers generally come through referral or existing relationships. Growth comes primarily from increasing the wagering volume of existing customers, not from signing up thousands of new ones.
The threshold for entry tells the rest of that story. Elite’s account materials require customers to expect to wager at least $20 million annually. Elite publicly confirmed the same minimum to the CHRB. That is $20 million a year just to meet the minimum expectation.
Some accounts are obviously far beyond it. Detailed California wagering data reported by Thoroughbred Daily News showed one account identified only as Elite 17 wagering roughly $53 million at Del Mar during 2023 and more than $650 million on United States racing through Elite during the year. That same reporting found that Elite 17 had negotiated economics at Del Mar that were more favorable than those available to other Elite customers.
I have no interest here in identifying who Elite 17 is. The identity is not necessary to understand the structure. What matters is that even inside a private wagering operation already serving some of the biggest bettors in the world, the economics are not necessarily the same from customer to customer. That brings us to the part I think most horseplayers need to understand.
Take a hypothetical $100 wager in a pari-mutuel pool with a 20% takeout.
The everyday customer bets his $100. The theoretical price of playing that pool is $20. Obviously a good handicapper can outperform the theoretical return and a bad one can do worse, but economically the published price of the bet is the published takeout. Nobody is sending the ordinary bettor a substantial portion of that $20 back after the race.
Now take a professional CAW customer wagering into that same pool.
His $100 enters the same pari-mutuel pool. The posted takeout does not magically disappear. What changes is what happens outside the pool after the wagering takes place.
The financial projections in the Curaçao material show approximately $2.659 billion in annual handle and approximately $399.6 million in player rewards. Divide one by the other and the projected player-reward expense works out to roughly 15% of handle across the entire operation.
That does not mean every Elite customer receives a 15% rebate on every wager. The evidence says exactly the opposite. Rates can vary by customer, track, pool, volume, timing and negotiated terms. TDN’s reporting concerning Elite 17 provides a documented example of one customer operating under economics different from those available to other Elite players.
But 15% is useful for illustration because it is what the aggregate Elite projection produces.
Here is the simplest way to look at it.
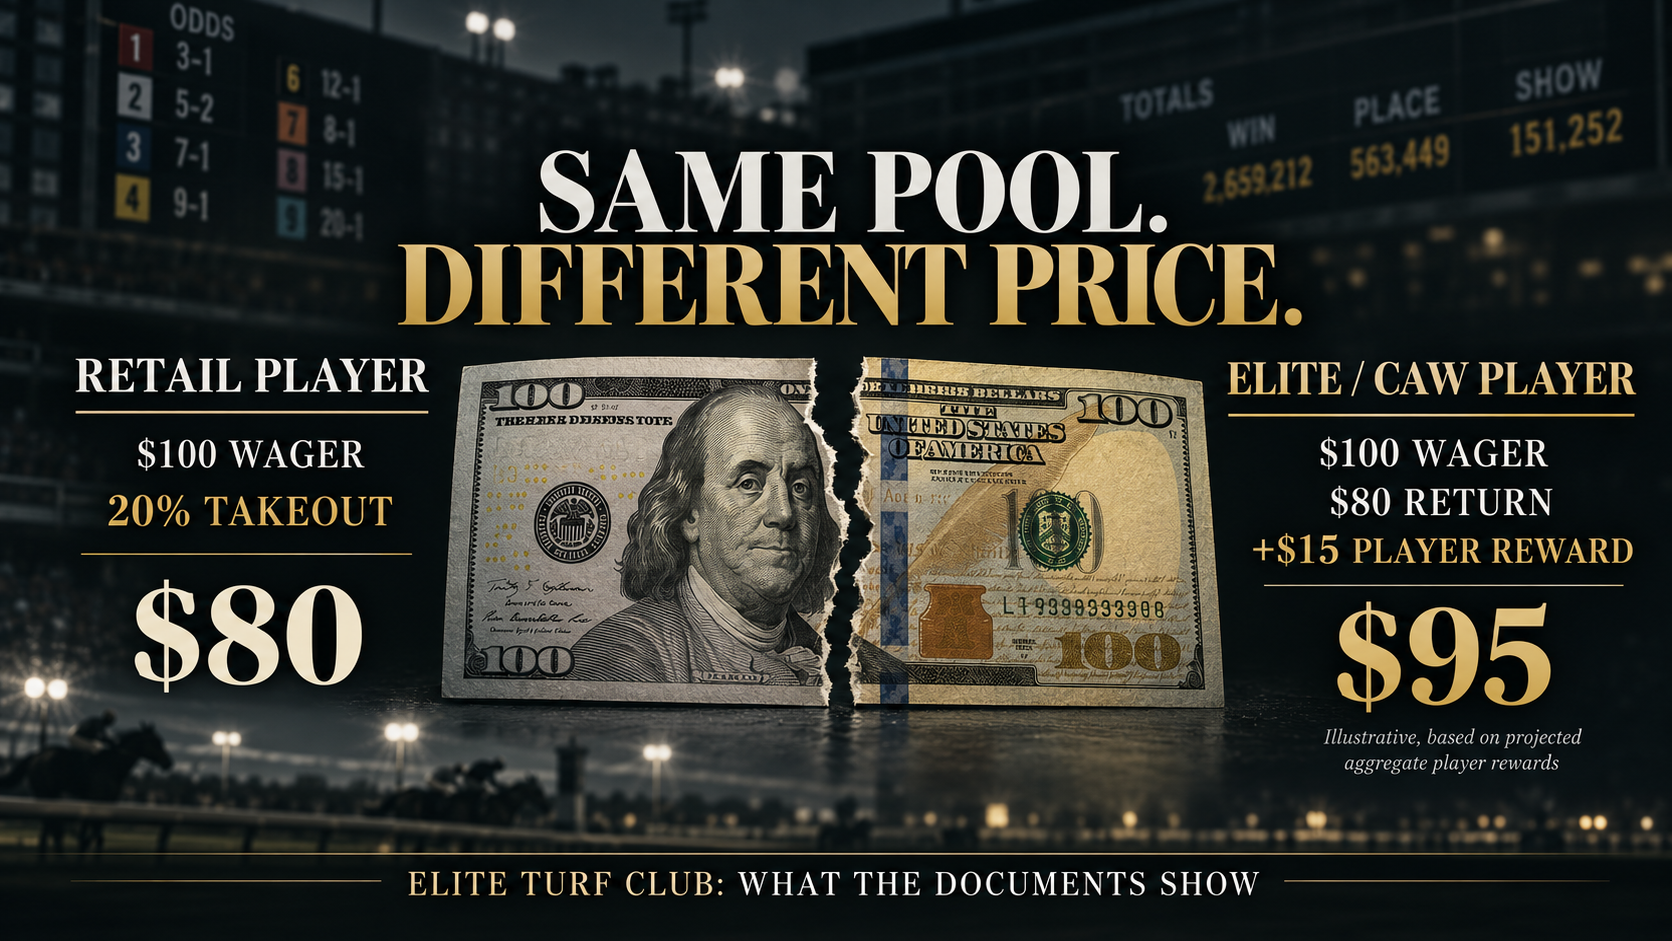
A retail player bets $100 into a 20% takeout pool. The theoretical return is $80. His theoretical cost is $20.
A CAW player bets the same $100 into the same pool. Assume he also returns $80 from the wagering itself, but receives $15 back through rewards. His total economic return becomes $95. His effective cost is $5.
Same pool. Same $100 entering the tote. Very different price once the entire transaction is finished.
Now change only one number.
Suppose the CAW player’s models and execution allow him to return $90 from the pool instead of $80. He still lost $10 on the wagering itself. Add the same $15 reward and his total economic return becomes $105. He lost at the windows and still made money. That is the part many people miss. They are playing in the same pool. They are not necessarily playing at the same price. That distinction is at the heart of the CAW business model.
The professional bettor does not necessarily have to show a profit on the raw pari-mutuel wagering in order to show a profit after rewards. The rebate changes the player’s break-even point. His models, technology, bankroll and wagering skill determine what he takes out of the pools. The rebate determines how much he can afford to lose before he actually loses money.
Elite itself used a 90% return assumption in explaining CAW economics to the California Horse Racing Board. Its example showed mathematically how one group returning more than the theoretical pool average necessarily changes the return received by everyone else because the game is pari-mutuel. Elite did not characterize that calculation as an admission that CAW is good or bad. Neither will I. The math does not require adjectives.
If the takeout is 20%, everyone collectively cannot receive 90 cents on the dollar from the wagering pool. If one segment does, another segment receives less. That is simply how pari-mutuel wagering works.
There is another side to this. Racing receives real money from CAW handle. Tracks receive host fees. Horsemen receive purse revenue. Liquidity increases. Elite has publicly argued that its business creates value for tracks through enormous wagering volume. That is not an imaginary benefit and pretending otherwise would make this discussion worthless. The question is not whether CAW brings money into racing. It does. The question is what that money costs the wagering ecosystem that generates it.
The Curaçao projections give us an unusually clear look at how the economics may work at scale. On approximately $2.659 billion in projected annual handle, Elite forecasts approximately $548.7 million in wagering revenue. It then projects approximately $131.9 million in simulcast fees, about $10 million in tote expense and approximately $399.6 million in player rewards.
The player rewards consume almost all of the contribution margin remaining after the direct wagering costs. That is worth reading again conceptually.
Billions of dollars are wagered. The racetracks and other providers receive their negotiated fees. Elite’s direct costs are paid. Then almost all of what remains in the projected economics goes back to the players. The projected EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) remaining at The Elite Turf Club N.V. is tiny relative to the handle. That does not mean the overall enterprise earns almost nothing. There are multiple entities involved and money moves between them. The financial statements show management fees and intercompany balances. Elite Turf Club LLC, Monarch Content Management, AmTote, racetracks and The Elite Turf Club N.V. perform different functions.
Where the total economic value ultimately resides across that structure is one of the questions we could not completely answer.
We can, however, identify much of the structure. Elite publicly told the CHRB that Elite Turf Club LLC is owned 80% by 1/ST Racing and 20% by NYRA. The Curaçao documents describe a separate ownership chain for The Elite Turf Club N.V. through BSF Trust Holdings and the Belinda Stronach family trust structure. Those are different legal entities and should not be casually lumped together just because both carry the Elite name.
The Curaçao business materials describe Elite Turf Club LLC as performing significant functions for the N.V. operation through a management agreement. Those functions include negotiating with racetracks over the terms under which Elite customers can wager into their pools, settling money with racetracks, conducting customer due diligence and handling customer funds through United States banking relationships.
Elite Turf Club LLC in turn uses Monarch Content Management for significant operational functions. Scott Daruty is identified publicly with both operations.
AmTote provides the wagering infrastructure. Elite told the CHRB that its customers develop an API to communicate with AmTote and that AmTote’s system is capable of processing up to 2,000 wagers per second from a single client. Elite also told the CHRB that its players receive the same tote feed as retail customers. That matters because there is a tendency whenever CAW is discussed to immediately jump from technological superiority to secret information. We found no evidence in these documents proving that Elite players receive secret final odds, privileged tote information unavailable to everyone else or some hidden look at the completed pool before wagering. They do not need any of those things for the documented advantages to matter. They have enormous bankrolls. They have sophisticated models. They have high-speed wagering technology. They can submit extraordinary numbers of combinations quickly. They have access to negotiated pricing unavailable to ordinary players. And they can churn capital at a scale most bettors cannot approach. That is enough of an advantage to discuss without inventing another one.
Elite also told the CHRB that each player’s wagering code must be approved by the individual racetrack before that customer is permitted to wager into the track’s pools. That matters because these customers are not merely opening an account and taking a publicly posted price. Their access is controlled and their economics can be negotiated.
TDN’s reporting on Elite 17 illustrates the point. Del Mar entered into an arrangement involving a significant upfront payment, wagering thresholds and an effective host-fee structure that left that player operating approximately a percentage point better than other Elite customers after the economics were accounted for. One percentage point does not sound dramatic until the customer is wagering hundreds of millions of dollars. One percent of $650 million is $6.5 million. This is why discussing CAW in percentages without discussing volume can be misleading. At this level, basis points become real money very quickly. It also explains why the idea that “CAWs get a 15% rebate” is too simplistic.
The aggregate documents suggest enormous rewards across the book, but there is no single Elite price. The price can vary by account. It can vary by track. It can vary by pool. It can vary depending upon when the bet is submitted. It can vary based upon volume commitments and separately negotiated arrangements. This is less like a rewards card and more like an institutional market where the largest participants negotiate their own cost of doing business.
That brings me to something else the documents raise. The 2022 and 2023 financial statements for The Elite Turf Club N.V. look like two completely different businesses. The 2022 statements report approximately $1.2 million in revenue and describe the company as being engaged in supporting e-gaming activities. The 2023 statements suddenly contain hundreds of millions of dollars in wagering revenue, promotions or player rewards, track fees and servicing expenses. That is not normal organic growth. Something changed.
It may have been accounting presentation. It may have been a contractual restructuring. It may have involved a change in which Elite entity was booking the wagering activity. The 2023 statements were also prepared on a different reporting basis and omit disclosures that might otherwise explain the transition. We could not find a document that definitively tells us what changed.
The Curaçao regulator itself appears to have wrestled with aspects of the corporate relationships and the role of the N.V. entity. Its later review materials sought clarification concerning the relationships among The Elite Turf Club N.V., Elite Turf Club LLC, Monarch and affiliated technology providers. That does not establish wrongdoing. A regulator asking a question is not the same thing as a regulator making a finding. But the unanswered question remains: why does the 2022 financial picture of N.V. look like a small support operation while the 2023 picture suddenly contains the economics of an enormous wagering operation? We don’t know. There is nothing wrong with saying that.
We also do not know the individual rebate schedules of every Elite customer. We don’t know every host fee negotiated with every racetrack. We don’t know the raw betting profitability of each account before rewards. We don’t know precisely where all of the enterprise profit eventually lands across every related entity.
And despite some of what is being said elsewhere, these documents do not establish that Elite’s owners secretly operate “house accounts” betting against the public. Elite has publicly stated that neither 1/ST Racing nor NYRA has an ownership interest in an Elite player. We found no evidence sufficient to contradict that statement. You also have to give NYRA extra credance for the CAW restrictions they imposed given the structure and economics of the big picture.
The documents do not establish corruption. They do not establish cheating. They do not establish that every CAW bettor receives the same deal. They don’t need to. The structure standing on its own is interesting enough.
Horse racing has built a wagering market in which the published price can be roughly 15%, 20% or 25% depending upon the pool while a tiny group of the largest bettors in the world can operate under individualized economics that reduce their actual cost dramatically.
There are rational arguments for doing this. These customers are intensely price sensitive. Lowering their price generates enormous volume. That volume produces host fees, liquidity and purses. Remove or substantially increase the price on the largest customers and some portion of that handle disappears. Elite itself has said that if takeout were universally reduced, its customers would continue playing but their wagering volume would decline materially. That is the industry’s argument in its strongest form. But it raises the obvious question. Why has racing chosen a relatively high published price combined with privately negotiated discounts for a handful of enormous customers rather than a meaningfully lower price available to everyone? Maybe the answer is that the current model generates more total revenue. Maybe it doesn’t. Maybe racing has become so dependent upon CAW churn that changing the model abruptly would do significant financial damage to tracks and purses. Maybe the long-term cost of extracting money from unrebatated players faster than they can replace it is greater than the short-term value created by the CAW volume.
Those are questions worth answering with data. What should no longer be acceptable is pretending the pricing structure does not exist.
A $100 bet is a $100 bet when it enters the pool.
It is not necessarily a $100 bet economically when the accounting is finished.
That is the part horseplayers have complained about for years, often without enough information to explain exactly what they were describing. The documents connected to The Elite Turf Club N.V., combined with Elite’s own public answers and California wagering records, give us a much clearer picture than we had before.
A very small number of sophisticated players wager enormous amounts of money. They are recruited selectively. They are expected to wager at extraordinary volume. Their access can require track approval. Their pricing can be individually negotiated. Their wagering technology can operate at speeds impossible for a human being manually entering tickets. The rebate can allow a player who loses before rewards to remain profitable after rewards. And those same players provide handle upon which racetracks and purses have increasingly come to depend.
That is not a conspiracy theory. That is the business model. What I still want to know is whether it is the best business model for the game. I think it is fair to say it is not the best business model for the bread and butter retail player.
Horse racing’s economic engine is wagering. The bettors fund the pools. Everything else flows from there. If the industry believes this structure is necessary, sustainable and ultimately beneficial to everyone participating in those pools, then there should be no reason to hide from explaining it.
Twenty customers. Billions wagered. Different prices for the same pools. Those numbers deserve more than slogans from either side. They deserve answers.
Key Documents Reviewed
- Curaçao License Application — Business Plan
- Curaçao License Application — Financial Projections
- The Elite Turf Club N.V. 2021 Financial Statements
- The Elite Turf Club N.V. 2022 Financial Statements
- The Elite Turf Club N.V. 2023 Financial Statements
- Certified Directors Register — The Elite Turf Club N.V.
- Shareholder / Corporate Structure Records
- Certified Trust Deed — The Belinda Stronach 445 Family Trust
- BSF Trust Holdings Inc. corporate records
- Elite Turf Club U.S. Wagering Account Application
- Elite Turf Club International Wagering Account Application
- Elite Turf Club Rules & Regulations
- Customer Due Diligence / Transaction Monitoring Policy
- Player Risk Rating materials
- Curaçao AML Manual
- Nevada AML Manual
- Curaçao Regulatory Final Report concerning The Elite Turf Club N.V.
- 2026 Updated Regulatory Memorandum concerning The Elite Turf Club N.V.
Past the Wire also reviewed related corporate, licensing, compliance and administrative records contained in the archive, as well as public CHRB materials and independently published reporting used for corroboration.
Comments